Check out omniroute.alphigma.com — Why OmniRoute Is the AI Gateway Behind Alphigma Quant AI
From Hypotheses to Alpha,
Engineered with Precision
SIGNAL
ALPHA
SIGMA
Advanced ML/AI for
Quantitative Research
Bridging modern deep learning with rigorous quantitative finance to create robust, uncorrelated alpha models.
Automated Pattern Discovery
with NexaPattern
The Intersection of
Alpha & Sigma
alphigma
NexaPattern
Automatic Pattern Detection Tool
Detect 35 famous market patterns, understand their technical setup, and quantify their statistical strength with a dynamic Confidence Factor.
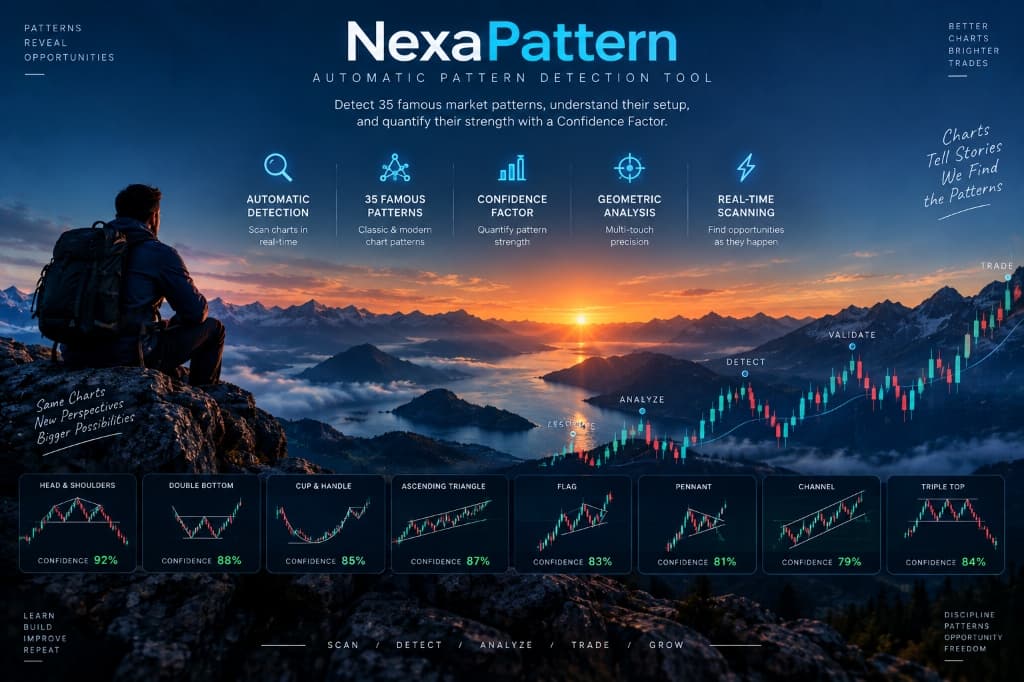
Core Capabilities
Nine high-value pillars powering our quantitative edge in systematic trading.
Portfolio Construction
Multi-signal blending, robust optimization, and transaction-cost-aware sizing.
Statistical Arbitrage
Market-neutral pairs, cointegration, and intraday stat-arb with decay modeling.
Live Research Tools & Models
Explore our interactive quantitative models, backtesting engines, and predictive screeners deployed in real-time.
Research
From hypotheses to evidence.
Empirical market studies, systematic backtests, factor decay models, and AI-driven alpha investigations conducted by Alphigma.
Premarket Gap-Fade Strategy
Testing the relationship between premarket momentum, liquidity imbalances, and intraday mean reversion in large-cap equities.
Temporal Graph Neural Networks for Multi-Asset Lead-Lag Detection
Combining dynamic graph embeddings and temporal transformers to model latent supply-chain propagation and cross-asset price lead-lag.
Cross-Asset Momentum & Factor Decay Dynamics
Testing the velocity of factor decay across liquid equities under varying volatility regimes, identifying optimal signal rebalancing intervals.
Insights
Ideas, observations and perspectives from Alphigma.
Articles, technical commentaries, AI architecture breakdowns, and quantitative tutorials published by the Alphigma engineering team.
Alphigma's AI Stack
A comprehensive exploration of the 5-layer architecture powering Alphigma: from curated datasets and multi-model routing via OmniRoute to collaborative agentic research and production products.
Deconstructing Modern Portfolio Theory: Limitations in Fat-Tailed Regimes
An exploration of why quadratic variance optimization breaks down during non-Gaussian liquidity crises and how Conditional Value-at-Risk (CVaR) bridges the gap.
Why OmniRoute Is the AI Gateway Behind Alphigma Quant AI
How Alphigma uses a multi-provider AI architecture to power its research, coding and content workflows with dynamic model routing, token optimization, and high-availability fallbacks.
The Team
Meet the experts behind our quantitative research and data science innovations.
Zoe CortexAI
FRONTEND DEVELOPER
Expert in React, TypeScript, and crafting premium user experiences for quantitative platforms.
James SentinelAI
BACKEND DEVELOPER
Specializes in high-performance trading engines, system architecture, and robust API development.
Noha SynapseAI
CLOUD ARCHITECTURE
Architecting scalable, secure, and resilient cloud infrastructure for large-scale data processing.
Zara PrimeAI
DATA SCIENTIST
Leveraging advanced machine learning and statistical modeling to uncover hidden Alphas and optimize position sizing.
Disclaimer: All information provided on this website is for educational and informational purposes only. It should not be considered as tax, legal, or investment advice. While we aim to provide accurate and up-to-date information, we make no warranties or representations regarding its accuracy, completeness, or reliability. Any reference to a specific stock, commodity, or other financial product is not a recommendation to buy, sell, or hold that financial product. The content on this site is not intended to be a substitute for professional advice. Always seek the advice of a qualified financial, legal, or tax advisor with any questions you may have regarding your financial situation.